
Nothing was priced at all.
The subsidiary was funded by transfers from the parent, recorded as intercompany balances that grow every month and were never characterised as anything. It is the most common situation and the easiest to fix early.
Solutions · Transfer pricing
Numminen Advisory builds the finance side of transfer pricing for investor-backed technology groups. Transfer pricing is how a group prices the transactions between its own companies: the services a parent provides to a subsidiary, the licensing of intellectual property, the cost of shared engineering, the intercompany loan.
We work alongside your tax adviser, and we do not replace one. The design of the model, the intercompany agreements that follow from it, and the accounting that has to produce the numbers every month sit on the finance side, and that is the part that usually has nobody looking after it.
This page is not tax advice. Positions on tax treatment belong with a qualified tax adviser, and we will tell you when you need one.
Cost plus, documented
Two separate questions get collapsed into one, and separating them answers most of what a growing company wants to know.
The documentation obligation has a size test. Under Finnish rules a company is exempt from preparing transfer pricing documentation while it stays within the small and medium-sized definition: fewer than 250 employees, together with turnover of no more than 50 million euros or a balance sheet total of no more than 43 million euros. The Tax Administration sets this out in its transfer pricing documentation guidance, which also notes that where documentation is required it must be produced within 60 days of a request.
Pricing your intercompany transactions properly does not have that test. The arm’s length principle governs how group companies transact with each other. The exemption above releases a company from preparing a documentation file. It does not release the transactions themselves from being priced correctly. Most companies at 15 to 60 people are exempt from the file and still have a pricing question to answer, because the transactions are already happening. The practical consequence is that the work worth doing early is cheap, and the work forced on you later is not.
In transfer pricing, AI keeps the evidence current. It pulls intercompany charges from each entity, tests them against the agreed markup and updates the local file from the ledger. At Numminen Advisory, Joanna Numminen sets the policy, reviews each result and approves any year-end adjustment before it is posted.
| Finance task | What AI does now | What stays with the CFO |
|---|---|---|
| Intercompany charges | Pulls charges from each entity and matches them to the agreements. | Whether the agreements still reflect how the group operates. |
| Markup testing | Tests service charges against the agreed markup each month. | The policy, and the response when an entity falls outside range. |
| Documentation | Updates the local file from the ledger and the agreements register. | The functional analysis and sign-off of the documentation. |
| Year-end adjustment | Calculates the adjustment that brings each entity into range. | Approval before posting, and the explanation to the tax adviser. |
Shapes we see often, not a specification.
A parent with one to four foreign subsidiaries, most often in the United States, the United Kingdom, another EU country or the Gulf region.
Engineering or product development concentrated in one entity while revenue is booked in another.
Intellectual property that was developed in one country and is being used to generate revenue in several.
Public funding in the parent company, which makes the allocation of shared costs a question for more than one authority.
Four patterns, all of which start as convenience.
Nothing was priced at all.
The subsidiary was funded by transfers from the parent, recorded as intercompany balances that grow every month and were never characterised as anything. It is the most common situation and the easiest to fix early.
A markup was picked and never justified.
Somebody applied cost plus five per cent because it sounded modest, and no record exists of why five, on which cost base, or for which services.
The agreements do not match the ledger.
Intercompany agreements say one thing and the accounting does another, which is the version auditors and tax authorities find most expensive to unpick.
The model is right and the accounting cannot produce it.
The policy requires an allocation the chart of accounts cannot generate, so the numbers get built by hand once a year in a spreadsheet nobody else can follow.
Design the intercompany model with your tax adviser: which entity does what, which costs it bears, how each flow is priced, and which method applies to each. Build the accounting so it produces those numbers every month rather than once a year. Make sure the intercompany agreements and the ledger describe the same arrangement. Reconcile both sides of every intercompany balance as part of the group close. Prepare the finance data a documentation file needs when the group grows into the obligation.
Take positions on tax treatment, sign documentation, or represent you in a tax audit. Those belong to a qualified tax adviser and we work with yours.
Transfer pricing design is usually scoped as project work rather than as a standalone diagnostic, because the sensible moment to do it is while the group structure is being built.
Where the question arrives inside a broader group problem, the group consolidation health check covers intercompany balances and the structure around them, and will usually tell you whether transfer pricing needs its own piece of work. Groups already on a retainer generally absorb this into the retainer.
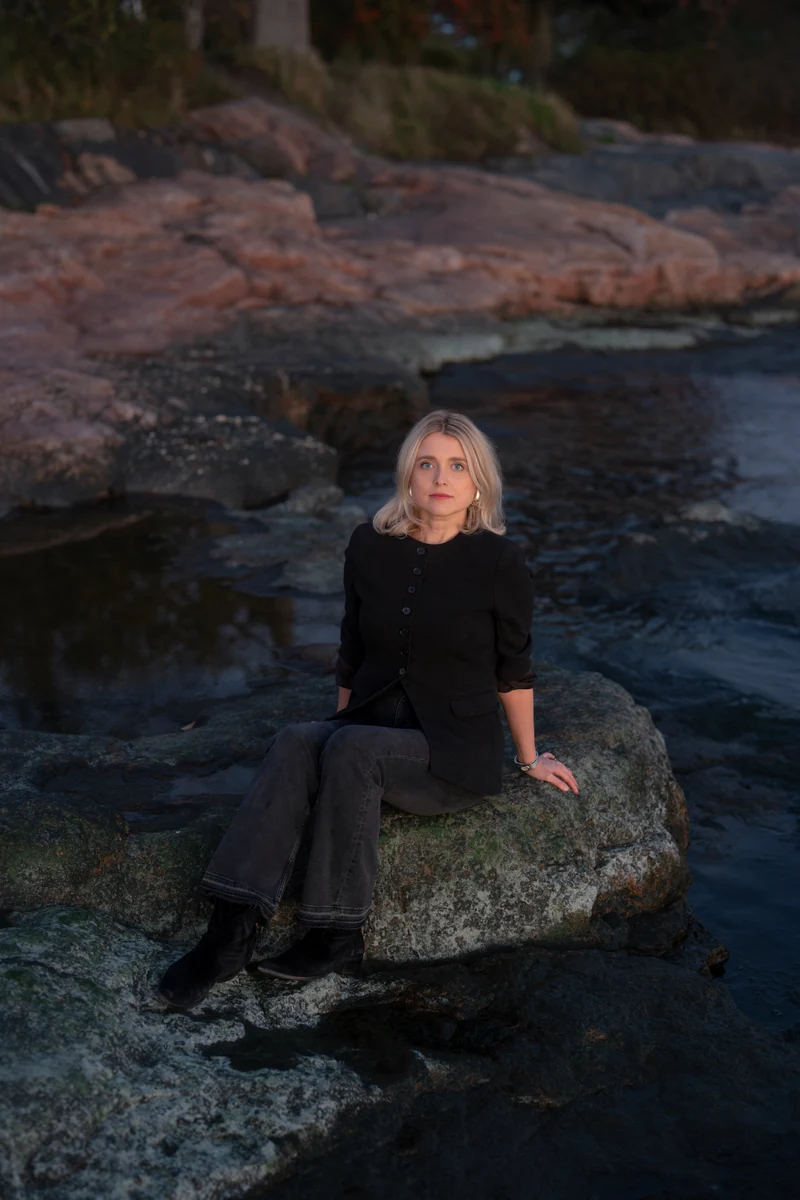
Numminen Advisory is founded and run by Joanna Numminen. She has built group structures and intercompany models in fast-scaling groups with entities across Europe, the Gulf and the United States, and has taken those structures through financial due diligence and post-deal integration. She is ACCA qualified and holds an MSc in International Accounting and Finance.
Transfer pricing is the setting of prices for transactions between companies in the same group, such as intercompany services, intellectual property licensing, shared costs and loans. Tax rules in most countries require those prices to reflect what unrelated parties would have agreed, which is known as the arm’s length principle.
In Finland the documentation obligation applies to companies outside the small and medium-sized definition: 250 employees or more, or turnover above 50 million euros together with a balance sheet total above 43 million euros. A company below that is exempt from preparing the file. Whether your specific situation qualifies is a question for a tax adviser, and it is cheap to ask once.
Exemption from the documentation file is not the same thing as being free to price intercompany transactions arbitrarily. The transactions are already happening and they are already being recorded somehow. Deciding how, deliberately, costs very little at this size.
When the second entity is incorporated, or immediately before. The design work is roughly a week when there is no history behind it, and it becomes a reconstruction exercise once two years of transactions have accumulated.
No. This is finance work: the model, the accounting behind it and the intercompany agreements matching the ledger. Tax positions belong to a qualified tax adviser, and we work alongside yours.
Usually the part that turns the policy into monthly numbers. A policy that the accounting cannot produce is a policy the group is not actually following, and that gap is what an auditor or an acquirer finds.
It can. Shared costs allocated between entities are also costs claimed against a project, and the two allocations have to tell the same story. Handling them as one question is cheaper than reconciling them later.