
First
Establish what a buyer will find.
A review of the areas above against the evidence that exists, resulting in a written list of findings ranked by how much they will cost, with the euros at risk quantified where they can be.
Solutions · Funding and diligence readiness
Numminen Advisory prepares investor-backed technology companies for financial due diligence, and keeps public funding reportable while the round is running. Financial due diligence is the examination an investor or an acquirer runs over your numbers before money moves, conducted by people paid to find what is wrong with them.
Companies rarely fail diligence on the substance of the business. They fail on whether the numbers can be evidenced, reconciled and explained by somebody other than the person who built them.
10of 12 sections
Dashed are outstanding
Patterns rather than requirements. A company that matches none of them can still need exactly this work.
A startup or international tech company getting ready for an investment round.
More than one entity, and often more than one country.
Equity alongside public funding or venture debt, which means more than one party with a claim on how costs were recorded.
A founder-CEO who carries the investor relationship alone and has never been through a financial due diligence process from the inside.
Diligence is a volume problem, and AI now carries most of the volume. At Numminen Advisory, AI checks each investor request against the data room index, bridges ARR to recognised revenue and drafts first answers for the Q&A log. Joanna Numminen decides what is released and answers for the numbers in front of investors.
| Finance task | What AI does now | What stays with the CFO |
|---|---|---|
| Data room | Checks each request against the index and lists what is missing. | What goes into the data room, and when. |
| Revenue and ARR | Bridges ARR to recognised revenue across the years under review. | How the revenue is explained, including every adjustment. |
| Investor Q&A | Logs each question and drafts a first answer from the ledger and the contracts. | The final answer, and the judgement on what to disclose. |
| Public funding reporting | Ties project costs in the ledger to the approved funding budget. | Sign-off of the cost report to the funder. |
Five areas absorb most of the questions, and the questions are the same every time.
Revenue. How it is recognised, when, against what contractual evidence, and whether the policy has been applied the same way for three years.
Cash and runway. The reconciled cash position at each period end, together with the assumptions the forecast carried at the time. What it assumed afterwards is a different document.
The group. Consolidated figures with intercompany removed, produced consistently for every period requested.
Costs and capitalisation. Which development costs were capitalised and on what basis, plus whether grant income was netted or recognised separately.
Obligations. Leases, loan covenants, grant conditions, employee equity, plus anything that turns into a liability under a change of control.
None of these is hard to answer with six months of notice. All of them are hard to answer in three weeks while the company is also being run.
Public funding carries cost eligibility rules and allocation logic that have to be designed into the accounting from the start. For example, Business Finland’s funding terms for R&D activities require the beneficiary to arrange its accounting so that the costs arising from the project can be itemised and their connection with the accounting and the reported costs can be verified, and give the agency the right to reject costs if project accounting has not been organised in accordance with the terms.
Retrofitting that structure afterwards is where the money gets lost. Hours that were never tracked against a project cannot be reconstructed credibly two years later, and costs that were eligible in principle become ineligible in practice because nothing in the ledger distinguishes them.
The same structure does double duty. A cost base that stands up to a public funding audit is already most of the way to standing up to an investor’s accountants.
Three things, in the order they usually happen.
First
Establish what a buyer will find.
A review of the areas above against the evidence that exists, resulting in a written list of findings ranked by how much they will cost, with the euros at risk quantified where they can be.
Second
Close the gaps that are worth closing.
Some findings are cheap to fix and some are historical and permanent. Knowing which is which before the process starts is worth more than fixing everything, because it changes what you disclose and when.
Third
Build the room and the story.
A data room organised the way accountants read one, with reconciliations that tie and a set of answers to the questions that are coming, prepared before somebody asks them under time pressure.
Quoted against scope before the work starts. A diagnostic over three to five days covering the reporting pack, revenue recognition, the cash and runway model and the evidence behind them. It ends in a written findings memo with a ranked remediation list.
Quoted against scope in the same way. The same shape, applied to Business Finland and other public project funding: cost eligibility, allocation logic, hour tracking, plus whether the project accounting would survive a cost audit.
Larger remediation, a data room build, or hands-on support through a live process is quoted as a project against scope. Companies inside a running transaction often take interim cover instead, which is a different page.
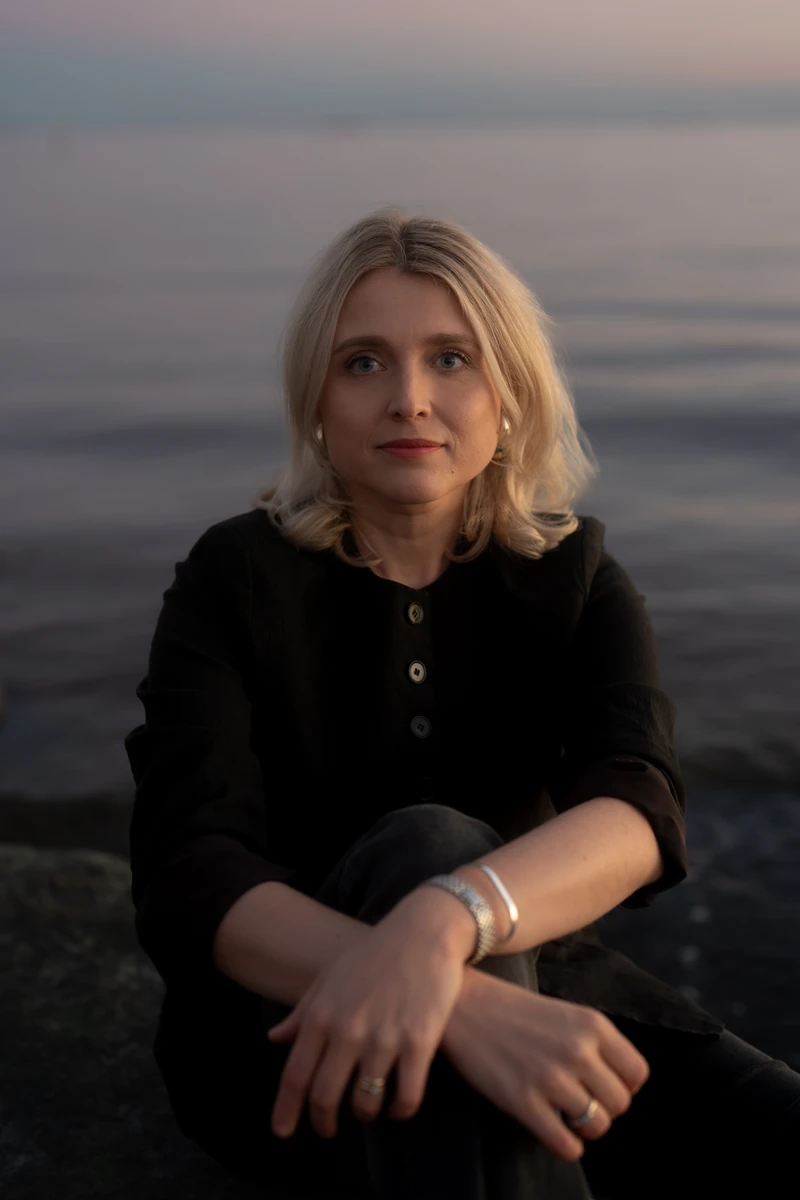
Numminen Advisory is founded and run by Joanna Numminen. She held senior finance through a global semiconductor company’s acquisition of an applied AI group, covering the statutory side, the financial due diligence and the post-deal integration. She has carried public funding through cost reporting and audit, and has built the reporting that investors and boards read in fast-scaling multi-country groups. She is ACCA qualified and holds an MSc in International Accounting and Finance.
Diligence findings do not usually kill a transaction. They move price, and they move it in one direction.
An unreconciled intercompany balance or a revenue policy that changed halfway through year two becomes a warranty, an indemnity, or a number subtracted from the valuation. The same finding, discovered six months earlier by your own side, is a housekeeping task nobody prices.
Financial due diligence is an independent examination of a company’s historical financial information, quality of earnings, working capital and cash position, carried out on behalf of an investor or an acquirer before a transaction completes. It is performed by accountants whose job is to find the problems, not to confirm the story.
Six months is comfortable and three is workable. Below that, the work happens during the process, which is when it is most expensive and least effective.
Your accounting firm keeps the books correctly under local rules. Diligence asks a different set of questions, about evidence, consistency and what a sceptical reader will conclude. The two rarely conflict, and one does not produce the other.
Yes. That is usually scoped as interim cover or a project rather than a diagnostic, because the volume is unpredictable and the timeline belongs to somebody else.
No. Grant consultancies do that well and several of them are partners. Our work starts once the money is awarded and the reporting obligations begin.
It complicates the cost base more than the round. Investors are used to Business Finland funding. What creates friction is a cost base where nobody can show which euros were claimed against which project and on what basis.
The work runs in English, which is the language of the data room, the diligence process and the investor relationship. Business Finland reporting is handled in Finnish where the programme requires it.